The question the title asks is more pointed than it appears. It does not ask whether Chilean fashion is good, innovative or internationally interesting. It asks whether a consumer in Chile who has heard about a Chilean independent fashion brand through a show, an Instagram post or a press mention can locate that brand’s product and purchase it without significant friction. The answer determines whether the brand’s domestic market, a fashion e-commerce market that generated US$2.39 billion in 2025, is a market the brand is actually participating in or a market it is performing for.
Fashion brands talk about their home markets as foundations: the audience that knows them first, supports them earliest and provides the community credibility from which international expansion is built. For that foundation to work commercially, home-market consumers need to be able to act on their interest. Seeing a brand at Chile Fashion Week and then not being able to find where to buy it produces a specific outcome: the brand generates interest and loses the transaction.
This article examines the domestic market access landscape for Chilean independent fashion brands across available channels, the structural characteristics of each channel, and the gap between a brand’s visibility in the Chilean fashion conversation and its purchasability for the Chilean fashion consumer.
Chilean independent fashion brands aspire to international distribution. The prior question is simpler: can someone in Santiago actually buy from them? This analysis examines domestic market access for Chilean independent fashion – the channels that exist, the structural obstacles, and the gap they produce.
What the Chilean Consumer Faces When They Try to Buy
The search experience
A Chilean consumer who discovers an independent local fashion brand through Chile Fashion Week or through an Instagram post takes a predictable next step: they search for the brand online. In most cases, the brand has an Instagram account with a contact link and a website. Whether the website allows a purchase depends on what kind of website it is. In 2025, an independent Chilean is likely to have one of three types of digital presence: a full direct-to-consumer (DTC) e-commerce site with a functional checkout, a portfolio or brochure site without a purchase mechanism, or an Instagram account whose link-in-bio points to a WhatsApp contact rather than a shop.
Each of these digital presences produces a different consumer experience. The DTC e-commerce site is the only one that enables immediate, frictionless purchases. The portfolio site generates interest with no direct conversion path; the interested consumer must contact the brand, wait for a response, and then arrange payment through whatever mechanism the brand uses for individual orders. The WhatsApp contact requires the consumer to initiate a personal transaction negotiation, which introduces friction that a significant proportion of potential buyers will not complete.
The WhatsApp transaction model is not unique to Chile. It is characteristic of independent fashion brands across markets where DTC infrastructure has not been built yet: the product is real, the quality is real, and the transaction happens, but it happens slowly and through a channel that does not scale. A brand that can close twenty WhatsApp transactions a week has a different commercial ceiling from a brand with a functional checkout that can process two hundred orders.
What the market data shows about where Chileans actually buy fashion
International platforms structurally dominate the Chilean fashion e-commerce market. The largest online fashion retailers in Chile by revenue are Shein, Mercado Libre and Temu, in that order. This is the competitive context in which Chilean independent brands operate: their domestic consumers already have a default online shopping infrastructure that connects them to global fast fashion at price points and delivery speeds that independent local production cannot match on those terms.
Falabella and Ripley, Chile’s dominant offline retailers, lead formal retail distribution. These department store chains have national footprints, and their buying criteria for new independent brand listings are comparable to what Omiren Styles has documented for major retail chains in other markets: minimum order quantities, compliance documentation, lead times, and sell-through guarantees that most independent brands cannot meet without prior wholesale infrastructure.
The relevant gap is between the consumer’s default purchasing behaviour, shaped by international platforms and department store chains, and the independent Chilean brand’s typical distribution model, which is either DTC through its own website, informal direct sales through social media or limited physical presence through multi-brand boutiques in Santiago. Consumers who want to buy from a Chilean independent brand are making an active choice to deviate from their default infrastructure. The more friction that deviation involves, the smaller the proportion of interested consumers who complete the purchase.
The Channels Available to Chilean Independent Brands
Direct-to-consumer websites
Among the Chilean independent fashion brands documented in current sources, some have built functional DTC e-commerce sites: Kika Neumann operates through kikaneumann.cl, and SISA through shopsisa.cl. Both are Santiago-based brands with established creative identities, and their websites allow purchases without requiring the consumer to start a WhatsApp conversation or find a physical stockist. These represent the more commercially developed end of the Chilean independent brand spectrum in terms of domestic market accessibility.
The DTC model for an independent Chilean fashion brand carries a specific set of operational requirements: payment processing in Chilean pesos with local card acceptance, domestic shipping infrastructure that reaches addresses across Chile, not only in Santiago, returns management, and customer service in Spanish. Each of these is a capability an internationally focused brand may underbuild if its aspiration is primarily export-led. A brand whose DTC site processes in US dollars and ships internationally but whose domestic shipping is slow or poorly documented has, in practice, prioritised the international consumer over the domestic one.
Multi-brand physical retail in Santiago
Santiago has a multi-brand boutique retail sector that can stock Chilean independent fashion, but its scale is limited compared with equivalent cities in Colombia, Brazil, or Argentina. Club Particular, the Puente Alto streetwear brand built around the Santiago neighbourhood where its founders grew up, stocks through multiple Santiago retailers according to published sources. Whatupwear, the pioneering Chilean street style brand, maintains a large loyal following and a physical stockist presence across the city.
Multi-brand physical retail is the domestic channel best positioned to build brand loyalty among consumers who discover products in person and who cannot or do not shop online. For an independent brand, the multi-brand boutique stockist channel also requires the most commercial preparation: the retailer needs a line sheet, MOQ terms, delivery documentation, and a reliable wholesale relationship with explicit terms. A brand without this documentation cannot enter this channel, regardless of product quality.
Mercado Libre and domestic marketplaces
Mercado Libre is Chile’s second-largest online fashion retailer by revenue and the dominant domestic marketplace. For an independent Chilean brand, listing on Mercado Libre is a way to reach domestic consumers already in the marketplace’s purchase flow without building the brand’s own DTC infrastructure. The marketplace’s commission structure and listing requirements are publicly documented; the barrier to entry for a brand with a finished product is lower than for department store retail.
The marketplace model’s domestic access advantage comes with a specific commercial trade-off: the brand’s identity competes with thousands of other listings, the price point is under pressure from international fast fashion listed on the same platform, and the brand relationship with the customer is mediated by the marketplace rather than direct. A consumer who buys through Mercado Libre is a marketplace customer first and a brand customer second. For a brand building long-term loyalty in its domestic market, the marketplace transaction is less valuable than the DTC transaction even when both produce the same unit sale.
What the Estallido Social Changed
The estallido social of October 2019 was a period of civil unrest in Chile that produced significant physical damage to retail infrastructure in Santiago’s commercial districts, including storefronts in Providencia and on Paseo Ahumada. The brands and retailers operating through those locations pivoted to direct-to-consumer models, in some cases permanently. This documented shift accelerated the DTC transition for independent Chilean fashion brands by removing the physical retail option that had been their primary domestic channel in the prior period.
The pivot to DTC produced both capability and constraint. The capability: brands that built functional e-commerce sites during the post-estallido period now have domestic market access that doesn’t depend on a physical location. The constraint: a DTC site requires ongoing investment in content, marketing, and fulfilment that a physical stockist relationship does not require once established. A brand that moved DTC in 2019 and 2020 has had five to six years to develop that capability. A brand that has not yet built DTC infrastructure is operating in a domestic market whose physical retail tier has contracted, without an equivalent digital replacement fully built out at the independent brand level.
The Home Market Access Gap
Visibility without purchasability
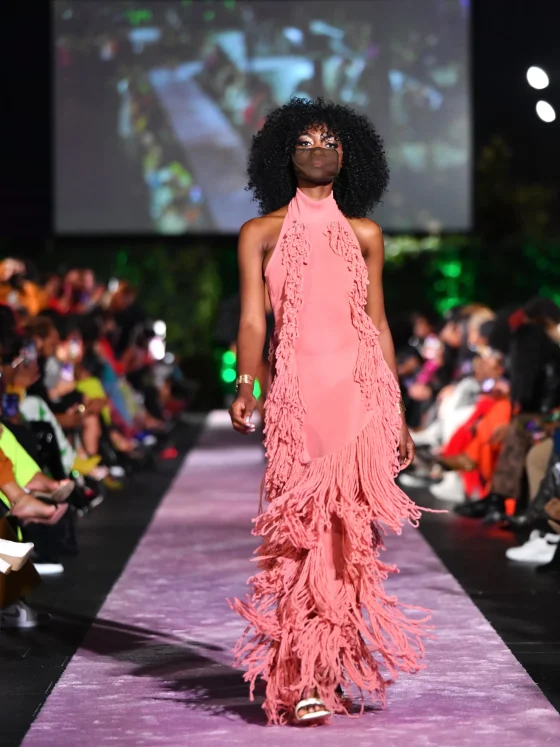
A brand that appears at Chile Fashion Week, generates Instagram posts, receives press coverage and has no functioning domestic purchase channel has achieved visibility without purchasability. An interested Chilean consumer who can’t find where to buy the product leaves the transaction. The brand has spent its show investment on an audience it cannot convert.
This gap is not unique to Chile. It appears wherever fashion events and social media create demand that the brand’s distribution infrastructure hasn’t been built to meet. The specific Chilean version of the gap is produced by the combination of three factors: independent brands that show at events before building their commercial infrastructure; a domestic retail landscape dominated by mass chains that are difficult for independent brands to access; and a DTC e-commerce sector where the default consumer platforms are international, leaving a structural gap for domestic brands whose own DTC capability is underdeveloped.
The gap has a specific cost. Each interested consumer who cannot find a purchase path is a transaction that does not happen and a customer who does not enter the brand’s database. For a brand at the stage where Chile Fashion Week represents a major visibility moment, the domestic consumer who saw the show or its coverage and wanted to buy is the most valuable customer available: warm, interested and in-market. Losing that transaction to friction in the purchase path is the most expensive possible outcome of a successful show.
The domestic market as the test case
The domestic market is also the test case for the brand’s commercial infrastructure. A brand that cannot satisfy a domestic consumer who is already interested and already motivated to complete a purchase in their own currency, in their own language, with local delivery, will struggle to satisfy an international consumer who faces additional barriers of currency conversion, international shipping and import costs. The domestic market access gap is not a separate problem from the international distribution ambition; it is the same commercial infrastructure problem at a simpler level.
As Omiren Styles established in its analysis of what commercial support Chilean fashion events publicly offer, the gap between a fashion event’s aesthetic offer and its commercial infrastructure for participating designers is the gap between being seen and receiving orders. The domestic market access question adds another layer: the gap between being seen and being purchasable by the consumer who saw you. Orders from buyers are the wholesale mechanism. Direct consumer purchases are the retail mechanism. Both require the brand to build a functional channel before the visibility event generates interest; the channel must convert.
What Domestic Market Access Requires
Building domestic market access for a Chilean independent brand in 2026 requires decisions across three channel types, each with different cost and complexity profiles.
The DTC website is the foundational requirement. A brand without a functional checkout, domestic payment processing, local delivery options and Spanish-language customer service does not have domestic market access; it has a portfolio site that generates interest it cannot convert. Building this capability requires investment that many independent brands defer in favour of show and event costs. The deferral produces the visibility-without-purchasability gap described above.
The multi-brand stockist relationship requires the commercial documentation that Omiren Styles has described in this series: a line sheet with local pricing, MOQ terms appropriate to boutique-scale buying in Chilean pesos, lead time documentation and a reliable wholesale process. A brand that has attended Chile Fashion Week without a line sheet prepared for local buyers has attended the event without the document that would allow a Chilean boutique buyer in the room to place an order.
The marketplace listing on Mercado Libre or equivalent domestic platforms provides lower-friction access to consumers already in the online shopping infrastructure, at the cost of brand identity dilution and margin compression from platform fees. It is the fastest domestic channel to activate and the least valuable for brand-building. Still, its presence alongside a functioning DTC site provides a complete domestic market access profile that covers both the consumer who searches specifically for the brand and the consumer who encounters it while browsing.
The Omiren Argument
Whether someone in a Chilean brand’s home market can buy its product is not a marketing question. It is a commercial infrastructure question, and the answer is a prerequisite for every other ambition the brand has. The brand that cannot convert the interested domestic consumer has no evidence base for the claim that it can convert an international buyer. The domestic market is the test. Building the infrastructure to pass that test is the commercial work that makes the creative work matter.
As Omiren Styles has argued throughout its coverage of fashion commerce and the Global South, the Global South made fashion and never got credit. Chilean independent designers who show their collections to a thousand people at a Santiago fashion event and cannot sell to those people afterwards have produced fashion that their own home market cannot access. The visibility is real. The gap between visibility and transaction is the commercial infrastructure problem that the evidence log, the line sheet, and the domestic market access channel are designed to close. Building those instruments is the work of building a fashion business rather than a fashion practice.
ALSO READ
- What Commercial Support Do Selected Chilean Fashion Events Publicly Offer?
- The Post-Show Evidence Log: What a Brand Should Record Before Calling an Event a Success
- A Line Sheet a Buyer Can Act On: The Information That Belongs Beside the Image
- The Distribution Gap: Where Independent Puerto Rican Beauty Brands Sell and What Gets in the Way
- The Global South Made Fashion. It Just Never Got Credit.
EXPLORE MORE
Read the full Buyer Intelligence coverage at Omiren Styles for ongoing analysis of domestic and international market access for independent fashion brands across Latin America, Africa and the Caribbean. Discover travel and heritage intelligence across Latin America, Africa and the wider diaspora at Rex Clarke Adventures.